
Banks adopt stricter rules to combat fraudulent accounts and illegal gambling in the financial system.
The Brazilian Federation of Banks (FEBRABAN) begins to apply, as of this Monday (27), a set of new rules to combat the use of the financial system by organized crime in Brazil. The measures come as a response to Operation Hidden Carbon, which dismantled a billion-dollar money laundering scheme involving the First Command of the Capital (PCC) and gas stations.
The guidelines are part of a "self-regulation" system for the banking sector, which complements legislation approved by the National Congress and official regulations from the Central Bank. The model seeks to close loopholes that have allowed large-scale fraudulent operations in the Brazilian financial system.
The following institutions participate in self-regulation: ABC Brasil, BMG, Bradesco, BTG Pactual, Citibank, Sicredi, Daycoval, BRB, Banco do Brasil, Banco do Estado do Pará, Banco do Estado do Rio Grande do Sul, Banco do Nordeste do Brasil, Fibra, JP Morgan, Banco Mercantil, Original, Pan, Safra, Santander, Banco Toyota, Banco Volkswagen, Banco Votorantim, Bank of China (Brasil), Caixa Econômica Federal and Itaú Unibanco.
“We are creating a milestone in the process of purging toxic relationships with clients who rent or sell their accounts and who seek the financial system as a channel to launder funds from scams, fraud, and cyberattacks, as well as to launder dirty money from crime. Banks cannot, under any circumstances, allow the opening and maintenance of dummy accounts, shell accounts, and illegal betting accounts, and that is why we are establishing mandatory procedures for all banks to regulate the sector and curb this type of crime,” commented Isaac Sidney, president of Febraban.
The deadline for fintechs operating without full authorization from the Central Bank to comply with regulations has been significantly reduced. The original period, which extended from 2020 to 2029, now has a limit of June 2026, following a suggestion from the banks themselves through FEBRABAN (Brazilian Federation of Banks).
New financial institutions that would fall under the more lenient rules face significant restrictions: they cannot open accounts or operate within the PIX system. Starting today, specific procedures come into effect for identifying and closing three types of problematic accounts: "dummy" accounts, opened with the account holder's consent allowing transactions by third parties; "cold" accounts, created with stolen personal data; and accounts linked to illegal betting sites.
One of the main focuses of the initiative is precisely to create efficient mechanisms to prevent banks from being used as intermediaries by illegal betting platforms, which move significant amounts of money through the national financial system.
In 2020, a law allowed payment institutions and fintechs to operate without prior authorization from the Central Bank. With the increase in electronic fraud, which reached R$ 10,2 billion in 2024, the need for greater control over these operations became evident.
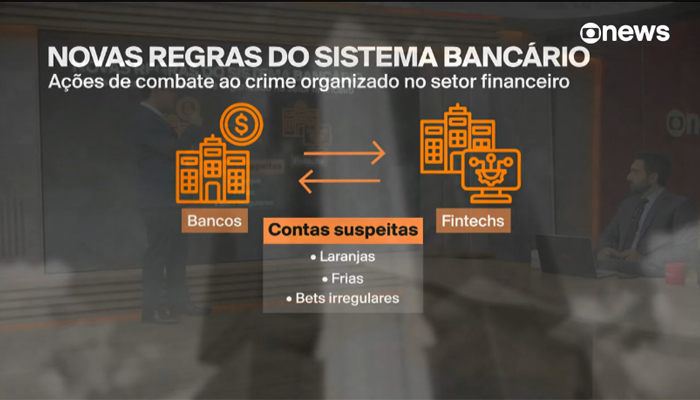
The self-regulation initiative already has the participation of 25 financial institutions, representing more than 90% of the banks holding deposit and checking accounts in the country. FEBRABAN intends to expand this participation to all 115 banks associated with the entity, with a special focus on retail banks.
Isaac Sidney, president of Febraban, highlighted the importance of this initiative: “The chain of illicit resources, the chain of resources that comes from organized crime or from scams, fraud, and attacks, this chain needs to be interrupted.”
FEBRABAN has established different guidelines for handling cold accounts and dummy accounts. In the case of cold accounts, banks will be more cautious about closing them immediately, recognizing that there is a victim involved – usually someone whose data was stolen for the fraudulent opening of the account.
On the other hand, accounts identified as "dummy accounts" will be treated more rigorously. FEBRABAN considers that these account holders have entered the world of crime by allowing their accounts to be used as a channel for illicit funds, whether to shelter, hide, or launder money.
The Central Bank recently implemented a set of 26 regulations to improve the regulatory framework for payment methods, in direct response to requests from FEBRABAN (Brazilian Federation of Banks). Among the measures is the requirement to block and suspend transactions in accounts identified as fraudulent.
Approximately 1.500 fintechs began operating without direct supervision from the Central Bank. While many reputable fintechs offer legitimate financial services, several of these companies remained outside the bounds of regulation and supervision, creating a loophole exploited by organized crime.
After thoroughly reviewing suspicious accounts, financial institutions will be required to report all identified and closed fraudulent accounts to FEBRABAN (Brazilian Federation of Banks) and the Central Bank. This monitoring will also extend to accounts linked to illegal betting sites, which represent approximately 40% of the betting market in Brazil, according to FEBRABAN data.
The question raised by experts is: "But there's no way to identify this, because since everything is done through transactions, isn't that monitored or monitorable?" This concern reflects the challenges faced by authorities in tracking the flow of illicit funds in the national financial system.
The president of Febraban, Isaac Sidney, reinforced the organization's position on the PIX system, highlighting that the mechanism does not favor criminal activities more than other payment methods available in Brazil. "We presented an argument showing that PIX is an instrument that is not used for crime, except by people who would use any other type of payment method," he stated.
Sidney emphasized the importance of the self-regulation recently implemented by the banking sector. “With this 'self-regulation' that we are putting into effect today, we understand that it is an important milestone to purify and eliminate from the banking system the corrupt relationships with clients and to identify who is or is not working for organized crime,” he stated.
Obligations of Banks under the new rules (effective from October 27th):
⇒ Strict policies and proprietary criteria for verifying fraudulent ("dummy" and "cold" accounts) and accounts used by irregular betting sites.
⇒ Refusal of transactions and immediate closure of illicit accounts, with notification to the account holder.
⇒ Mandatory reporting to the Central Bank, allowing the sharing of information between financial institutions.
⇒ Monitoring and supervision of the process by Febraban's Self-Regulation body, which may request, at any time, evidence of reporting and closing of illicit accounts.
⇒ Active participation from the banks' fraud prevention, money laundering, legal, and ombudsman departments, which also participated in the drafting of the new rules.
⇒ In case of non-compliance, there will be penalties, ranging from prompt adjustment of conduct and warnings to exclusion from the Self-Regulation system.
Institutions participating in Febraban's Self-Regulation: ABC Brasil, BMG, Bradesco, BTG Pactual, Citibank, Sicredi, Daycoval, BRB, Banco do Brasil, Banco do Estado do Pará, Banco do Estado do Rio Grande do Sul, Banco do Nordeste do Brasil, Fibra, JP Morgan, Banco Mercantil, Original, Pan, Safra, Santander, Banco Toyota, Banco Volkswagen, Banco Votorantim, Bank of China (Brasil), Caixa Econômica Federal and Itaú Unibanco.
Additional obligations of banks:
⇒ Maintain internal policies in place for identifying and closing suspicious accounts.
⇒ Submit a declaration of conformity to the Self-Regulation Board of Febraban, prepared by an independent area, Internal Audit, Compliance or Internal Controls.
⇒ To promote, with the assistance of Febraban, communication, guidance and education initiatives for the prevention of scams and fraud.
Position of the Director of Self-Regulation at Febraban, Amaury Oliva:
"The growing and alarming increase in fraud and scams within the Financial System demands the implementation of effective measures, especially regarding the use of accounts known as 'Pass-Through Accounts,' better known as 'Dummy Accounts.' These accounts currently receive and move funds resulting from illegal or suspicious transactions, enabling various criminal practices."

