
Central Bank contradicts itself: director calls bets "central" in debt, president doesn't mention the sector.
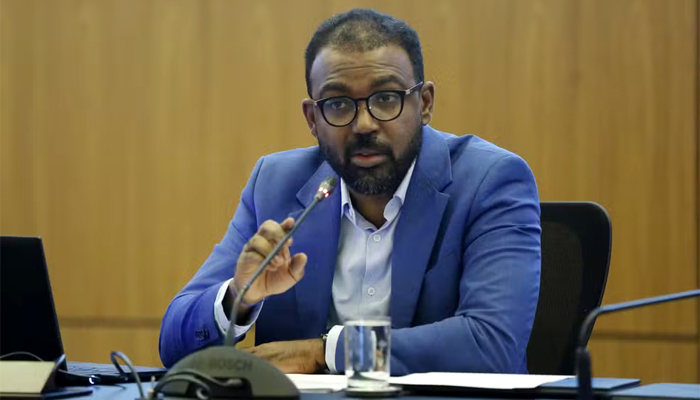
The director of supervision at the Central Bank, Ailton de Aquino Santos, stated this Tuesday (1st), at the Zetta Summit 2026, that it is “indisputable” that bets are a “central element” of the indebtedness of Brazilian families, even classifying as “fake news” any position that denies this contribution. The statement, however, directly clashes with the diagnosis presented publicly by the president of the institution itself, Gabriel Galípolo, just eight days earlier.
Aquino spoke during the Zetta Summit 2026 event – “Stability, financial citizenship and competitiveness”, held in Brasília. The director of the Central Bank advocated for a closer look at the health of Brazilian credit and borrowers, according to a report by VALOR.
The diagnosis that already exists — and doesn't mention bets
At the opening of Febraban Tech 2026, on August 24th, Galípolo dedicated a significant portion of his speech to detailing, with data, the causes of household over-indebtedness. He identified three key factors: revolving credit card debt, private payroll loans, and unsecured personal loans. Sports betting was not mentioned even once.
The figures presented by Galípolo are specific and verifiable: of the 96 million credit card users in the country, 52,8 million carry debt in revolving credit or installment plans with interest, with monthly rates above 15%. The average commitment of family income to credit card bills jumped from 38,5% to 54%. In private payroll loans, the portfolio more than doubled in just over a year — from R$ 41 billion in March 2025 to R$ 102 billion in May 2026, an increase of 145% —, with delinquency rising from 5% to 6,7% and interest rates jumping from 40,9% to 57%. Non-payroll personal credit reached approximately R$ 400 billion in outstanding balances.
According to the president of the Central Bank, the logic is straightforward: "the credit that a financial institution grants is the debt that someone else has taken on." The problem is concentrated where credit has grown faster and where interest rates are higher—not in an entertainment product that doesn't grant credit to anyone.
Bernardo Freire, legal advisor to ANJL and founding partner of BetLaw, commented on the irresponsibility of the Central Bank director in commenting on a serious matter without objective evidence.
“A director of the Central Bank, especially when speaking publicly about a regulated sector, should base their statements on official data and objective evidence, and not on personal opinions — particularly when these contradict the statements of the Central Bank president himself and the official data available on the betting sector,” commented Freire.
A scaling problem
Even if there were some degree of overlap between bettors and debtors—which in itself would not establish causality—the proportion does not support the label of "central element." The GGR (gross revenue) of the entire regulated betting market totaled R$ 37 billion in 2025. This is already net revenue from prizes paid, it does not represent money "withdrawn" from the economy, and it is an annual flow for the entire sector. Compared in isolation to the balance of non-payroll-deducted personal credit—around R$ 400 billion, more than ten times greater—or to the jump of R$ 61 billion in private payroll-deducted loans alone in just over a year, the difference in order of magnitude is evident. To call something ten times smaller than a single line of credit, among several, a "central element" is a statement that the institution's own numbers do not support.
The trend is going in the opposite direction.
There is also a piece of data that directly weakens Aquino's thesis: the average ticket price of Brazilian bettors is falling, not rising. It dropped from R$122,00 in 2025 to R$108,27 in the first half of 2026—a decrease of more than 11%. If betting were, in fact, a growing driver of debt, the expected pattern would be the opposite: average spending rising along with income commitment. Market data shows exactly the opposite.
Confusion between categories
There is a fundamental conceptual error in the director's statement: bets are not a credit instrument. They do not lend money, do not charge interest on outstanding balances, and do not generate contractual debt like credit cards, payroll loans, or personal loans. It is possible—and legitimate—to discuss whether bettors use income that should be used to pay off debts to gamble, or whether they resort to credit to finance bets. But this is a behavioral hypothesis about income allocation; it is not equivalent to saying that bets are a "central and indisputable element" of indebtedness in the same sense that revolving credit cards and payroll loans are—which are, in fact, the instruments of debt themselves.
The point that deserved more attention — and was overlooked
Ironically, the most consistent part of Aquino's speech was the least discussed: the questioning about digital wallets that could "bypass and supply credits for betting." This is a real issue for oversight—traceability of flows via Pix Crédito and transparency of CET (Total Effective Cost)—but it's a matter of payment methods and fraud prevention, distinct from attributing the cause of indebtedness to betting as a category. By merging the two arguments into a single categorical sentence, the speech loses technical precision precisely where it needs it most.
The underlying issue
If the monetary authority itself, through its president, presented a detailed diagnosis of household debt without mentioning bets, then calling the sector a "central and indisputable element" eight days later—within the same body, under the same authority—is not merely a differing opinion. It is an internal contradiction that the institution should clarify: which of the two interpretations represents the Central Bank's position?

