
Draft laws propose increased taxation on betting, and experts question their constitutionality.

The National Congress is analyzing two draft laws that seek to increase the tax burden on fixed-odds betting, known as "bets." Draft laws 5.076/2025 and 5.473/2025 propose increasing the tax rate currently set at 12% by Federal Law No. 14.790/2023. The proposal has generated questions about its constitutionality and impacts on the recently regulated market.
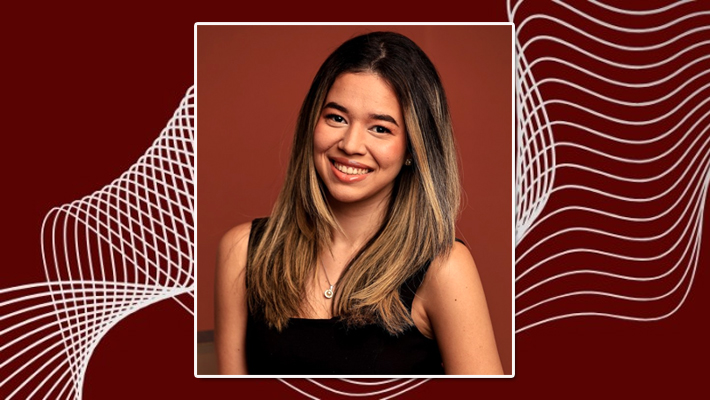
Attorney Yasmin Farias produced an opinion on the unconstitutionality of increasing the tax burden on fixed-odds betting, focusing specifically on Bills 5.076/2025 and 5.473/2025. The document provides a legal and economic-regulatory analysis of the issue, considering the impacts on the market and the competitive structure of the sector.
The proposed changes aim to double the current tax rate, raising it to 24% on GGR (Gross Gaming Revenue), which could increase the sector's total tax burden to approximately 72,25%, according to technical analyses.
Bills 5.076/2025 and 5.473/2025 seek to modify the taxation established by Law No. 14.790/2023, which regulated the fixed-odds betting sector in the country. The justification presented by the proponents is based on the argument that betting constitutes a "social risk" activity, and that the increase in taxation would have an extra-fiscal character.
Proponents of the proposal argue that raising the tax rate aims to discourage consumption and direct additional resources towards financing public health policies. A legal opinion prepared to analyze the proposals examines whether they respect the general principles of tax law, the constitutional limits of the power to tax, and the structuring principles of the economic order.
The regulated betting market in Brazil officially began operations on January 1, 2025, following the consolidation of the regulatory framework established by Law 14.790/2023. This legislation defined duties, obligations, oversight parameters, authorization requirements, and the tax regime applicable to the sector.
The report warns that an abrupt and disproportionate tax change, before the regulated market has stabilized, could create risks to the sector's sustainability, tax collection efficiency, and regulatory coherence.
In its constitutional analysis, the document highlights that Article 145, §1, of the Federal Constitution establishes that "whenever possible, taxes will be personal in nature and will be graduated according to the taxpayer's economic capacity."
This provision enshrines the principle of ability to pay, which guides the entire national tax system. The principle dictates that the State should levy taxes according to the economic capacity of taxpayers, so that those with greater wealth contribute in a higher proportion than those with less favorable economic situations.
Taxation in the fixed-odds betting sector presents a complex structure that directly impacts the assets of operating companies. According to a technical analysis, companies in the sector face difficulties in supporting a tax burden considered onerous, especially in a market that is still in the consolidation phase in Brazil.
The regulated fixed-odds betting market is in its early stages, less than a year after the first authorizations to operate the service were granted. In this context, the application of the current 12% tax rate on GGR already represents a significant part of a broader tax structure affecting operators.
According to the data collected, the total potential tax burden on the sector could reach approximately 60%, not considering other essential operational costs. This percentage results from the combination of various taxes and contributions levied on different calculation bases, creating a complex tax system for companies in the segment.
Among the taxes that make up this burden, the 12% rate on the GGR stands out, which is sectoral and social in nature. This tax is levied on the gross revenue from bets, after deducting prizes paid and income tax withheld on prizes distributed to bettors.
In addition to this specific taxation, operators are also subject to an oversight fee that varies according to value ranges, from R$ 54.419,56 to R$ 1.944.000,00. This fee is also calculated based on the gross revenue from bets, with the same deductions applicable to the GGR (Gross Revenue Guarantee).
In the context of federal taxes on profits, companies in the sector face the incidence of Corporate Income Tax (IRPJ), with a rate of 25% on actual or presumed profit, and the Social Contribution on Net Profit (CSLL), with a rate of 9% on the same tax base as the Income Tax.
The tax burden is supplemented by the PIS and COFINS social contributions, which total 9,25% of companies' gross revenue. At the municipal level, operators are also subject to the Service Tax (ISS), whose rate can vary from 2% to 5%, depending on the legislation of each municipality.
The legal opinion points out that Bills 5.076/2025 and 5.473/2025 present potential unconstitutional flaws. The document highlights that the proposals, although declaring legitimate objectives such as combating gambling addiction and financing public health, lack adequate technical justification.
According to the opinion, taxation in Brazil must follow specific constitutional principles, even when it has an extra-fiscal purpose. The legal analysis emphasizes that extra-fiscal taxation must adhere to the principles of reasonableness, proportionality, and prohibition of confiscation, otherwise it risks being misused.
According to the opinion, although combating gambling addiction and financing healthcare are constitutionally valid objectives, the proposed increase does not demonstrate proportionality between the rise in the tax rate and the effectiveness of the intended result.
A critical point highlighted in the document is the absence of technical studies or economic impact assessments proving that the increase in tax rates will result in a reduction in gambling addiction or a sustainable increase in revenue. This gap undermines the extra-fiscal justification for the legislative proposals.
The Brazilian Supreme Federal Court has already ruled on the limits of state power in tax matters. In a relevant judgment, Justice Celso de Mello stated: “The State cannot legislate abusively, since all norms emanating from public power – whether or not they concern tax matters – must conform to the clause that enshrines, in its material dimension, the principle of substantive due process of law (Brazilian Constitution, art. 5, LIV). The principle of proportionality qualifies as a parameter for assessing the very material constitutionality of state acts. In this case, tax legislation is endowed with the necessary coefficient of reasonableness.”
According to data from a study commissioned by the Brazilian Institute for Responsible Gaming (IBJR) and the National Association of Games and Lotteries (ANJL), the betting sector is expected to generate more than R$ 9 billion in federal and municipal tax revenue in 2025. Licensed companies have already declared their own investments of approximately R$ 7,5 billion in the country.
The technical study prepared by these entities also indicates that the regulated market has the potential to generate up to R$ 28 billion in additional demand in other segments of the economy. In terms of employment, it is estimated that the sector is responsible for thousands of direct and indirect jobs, predominantly highly skilled and with above-average remuneration.
Conclusion
At the end of the opinion, lawyer Yasmin Farias concludes that the proposals present material flaws of unconstitutionality due to the absence of minimal technical justification, constituting a violation of substantive due process, which requires rationality and proportionality in legislative choices, in addition to violating the principle of ability to pay and the principle of tax equality. The imposition of a disproportionate and potentially confiscatory tax burden and the affront to the principles of free enterprise and free competition are also highlighted.
“We recommend holding public hearings with the participation of representatives from the sector, specialists and economists, revising the legal text in order to adapt the rates to the economic reality and the stage of regulatory maturity of the market, and maintaining a balance between revenue collection and the viability of the regulated market, an indispensable condition to combat the illegal market and protect consumers,” comments Yasmin Farias.
"Otherwise, the bills under review may be considered materially unconstitutional, as they directly violate the structuring principles of the economic order and the national tax system," he concludes.
